Common Money Mistakes People Make in Their 20s
Money mistakes in your 20s are rarely about carelessness. They are about timing. Income is at its lowest, independence is brand new, and nobody has explained how the system works, so ordinary decisions quietly set patterns that last for decades. The good news is that the common money mistakes of this decade are the same few over and over, and each one has a practical fix that costs very little to start. This guide ranks them, shows what each one really costs, and ends with a ninety-day plan you can begin this week.
Why Your 20s Matter So Much
You will almost certainly never again have so little money and so much time. Time is the asset that does the heavy lifting in personal finance, because savings and investments grow on top of their own earlier growth. Habits matter just as much. The way you handle a first salary, a first credit card, and a first raise tends to become the default for everything that follows. Fixing a habit at twenty-five is easy. Fixing it at forty-five, after it has hardened and the debts have grown, is much harder.
The Cost of Each Mistake at a Glance
| Mistake | What it costs you | The first fix |
|---|---|---|
| No emergency fund | Every surprise bill becomes debt | Automatic transfer to a separate savings account |
| Carrying card balances | Interest that often runs into double digits | Pay in full, and attack the highest rate first |
| Waiting to save for retirement | Years of compounding you cannot buy back | Start with any amount and take any employer match |
| Lifestyle rising with every raise | A bigger income with the same savings | Decide the split of each raise before it arrives |
| Not tracking spending | Money disappears without a decision | One monthly review of where it went |
| Ignoring your credit record | Higher borrowing costs and rental hurdles | Pay on time and check your report yearly |
Mistake 1: Skipping the Emergency Fund
The most common reason young adults have no emergency savings is not low income. It is priority. The money exists, but it gets absorbed by everyday spending before it can be saved. Without a cushion, a broken phone, a medical bill, or a gap between jobs pushes you toward credit card debt at the worst possible moment.
The fix is to start small and automate. Many planners suggest building toward three to six months of essential expenses, but the first target can be one modest month. Set up an automatic transfer on payday into a separate savings account that lets you withdraw without penalty, so it is easy to reach in a real emergency and slightly inconvenient to raid for a weekend trip. The full method is laid out in starting an emergency fund from scratch.
Mistake 2: Carrying Credit Card Balances
A credit card is a convenient tool and an expensive loan. When a balance rolls over, interest is typically charged at a high rate, and paying only the minimum keeps you in debt for years while most of each payment goes to interest. If you already carry a balance, the math strongly favors paying it down before almost anything else, because no ordinary investment reliably earns more than the interest you are being charged.
Pay the full statement balance every month whenever you can. If that is not possible yet, list every debt, pay the minimum on all of them, and put every spare amount toward the one with the highest rate. The approach is covered in detail in paying off debt faster, including how to do it without a large income.
Mistake 3: Waiting to Save for Retirement
Retirement feels impossibly far away at twenty five, which is exactly why starting then is so powerful. Consider a simple illustration, using an assumed average growth of six percent a year, which is not a guarantee. Saving one hundred a month for forty years would grow to roughly one hundred ninety nine thousand, on total contributions of forty eight thousand. Waiting ten years and saving the same amount for thirty years would grow to roughly one hundred thousand, on contributions of thirty six thousand. Ten years of delay costs about half of the final result, even though you only skipped a quarter of the contributions.
The lesson is not that you need a large sum. It is that you need to start. Begin with any amount you will actually keep paying, and if your employer offers a retirement plan with matching contributions, take the match, since it is effectively part of your pay. Retirement rules and products differ by country, so check what applies where you live and consider speaking with a qualified adviser.
Mistake 4: Letting Lifestyle Rise With Every Raise
Lifestyle inflation is the quiet habit of upgrading your spending every time your income rises, until a bigger salary buys you nothing extra. A better apartment, a newer phone, and more frequent dining out are each reasonable alone. Together they can absorb an entire raise before a single extra unit reaches your savings.
The fix is to decide the split in advance. A common rule of thumb is to direct at least half of every raise to savings, investments, or debt, and let the rest improve your life. Making that decision before the raise arrives removes the temptation to rationalize later.
Mistake 5: Never Tracking Where Money Goes
Most people who say they have no budget also say they cannot understand where their money goes. These are the same problem. You do not need a complicated system. A simple monthly review of your income, your fixed bills, and your spending by category is enough to reveal subscriptions you forgot, habits that cost more than you assumed, and room to redirect toward goals. If you want a structure, a simple monthly budget shows how to build one in an hour.
Mistake 6: Ignoring Your Credit Record
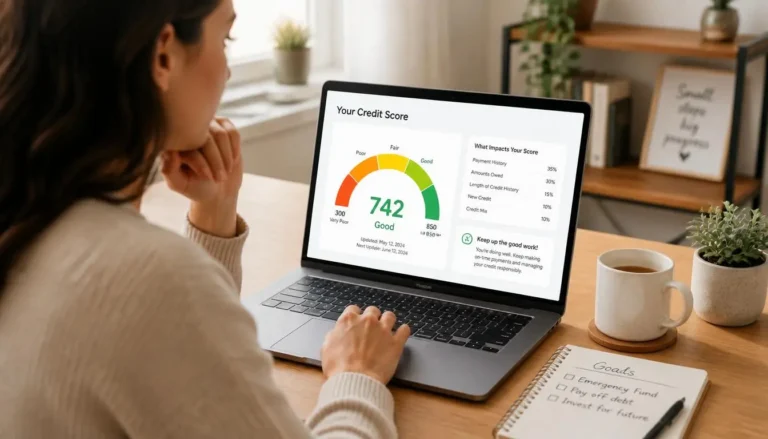
A credit record affects more than loans. It can influence rental applications, insurance pricing, and in some industries even job screening. The basics are unglamorous: pay every bill on time, keep balances low relative to your limits, and avoid applying for every offer that arrives. Check your report once a year for errors. The mechanics behind the score are explained in understanding your credit score, and the same habits that protect your credit also protect your cash flow.
Mistake 7: Staying Away From Investing Out of Fear
Cash feels safe, but over long periods inflation steadily reduces what it can buy. Many young adults stay on the sidelines because investing seems complicated or risky. You do not have to become an expert. Learn the basics first, understand that prices rise and fall in the short term, favor low cost and diversified options, and invest only money you will not need for several years, after your emergency fund is in place. If you feel unsure, a qualified adviser can help you decide what suits your situation.
A Quiet Eighth Mistake: Having No Written Goals
Many of the mistakes above share one root cause, which is that money has no job to do. When savings have no destination, they feel optional and are easy to spend. Write down three goals with dates and amounts, for example a first month of emergency savings by a set date, a card balance cleared by the end of the year, and a first retirement contribution this quarter. Short term goals give you quick wins, and a long term goal gives the small monthly decisions a reason to matter. A goal you can measure is far easier to protect than a vague wish to be better with money.
If You Have Already Made Some of These
Most people reading this list will recognize at least three. That is normal, and it is fixable. The decade is long, and a single year of steady correction does more than a decade of guilt. Pick the one mistake that costs you the most today and fix only that first.
Your First 90 Days
Days 1 to 30: See Everything
List every account, debt, and recurring bill. Track your spending for one full month. Open a separate savings account and set up a small automatic transfer, even if it is only a token amount.
Days 31 to 60: Stop the Bleeding
Cancel subscriptions you do not use. Rank your debts by interest rate and send every spare amount to the highest one. Raise your automatic savings transfer by whatever your tracking showed you can afford.
Days 61 to 90: Build the Habits
Start or increase a retirement contribution and claim any employer match. Decide in writing how you will split your next raise. Check your credit report, schedule a monthly money review, and put the next review on your calendar before you close this page.